 Blog
How to Evaluate Sportfish Engine Hours
Learn how to evaluate sportfish engine hours accurately. Understand duty cycles, maintenance history, and diagnostic tools to assess true engine condition.
What Yacht Brokerage Transparency Standards Actually Require
Fiduciary Duty in Yacht Brokerage: What It Means for Your Deal
A Transparency Checklist for Holding Your Broker Accountable
Last Updated: September 24, 2026
Yacht brokerage transparency standards are the disclosure, documentation, and representation practices that let a buyer or seller see exactly who is being paid, by whom, and for what, at every stage of a transaction: written commission disclosure, signed agency agreements, documented escrow movement, and condition reporting that stands up to an independent survey.
Fiduciary duty in yacht brokerage is the legal obligation to put the client's financial interest ahead of the broker's own: disclose material facts, avoid undisclosed conflicts, and account for all funds handled. It is the standard for professional conduct, not a courtesy.
Dual agency occurs when a single brokerage represents both buyer and seller in the same transaction. It is legal in many states with written consent, but it is the largest source of undisclosed conflict in yacht transactions.
Yacht broker commission disclosure means stating, in writing and before the listing goes live, the total commission percentage, how it is split between listing and selling broker, and who bears it at closing. Vague references to "standard commission" are not disclosure. A number without a payer is not disclosure either.
A disclosure that survives scrutiny answers five questions in writing:
Total rate. The full percentage or flat figure, stated as a number, not a range.
Split. How the total divides between the listing brokerage and the selling brokerage, and whether a co-broke arrangement applies if another brokerage brings the buyer.
Payer. Who actually pays at closing, typically the seller from proceeds, but the agreement should say so explicitly rather than leave it to convention.
Trigger. The event that earns the commission: a signed purchase agreement, a completed closing, or something else. These are not the same, and the difference matters if a deal collapses after survey.
Duration and tail. How long the listing runs, and whether the broker is owed a commission on a buyer they introduced if the seller sells to that buyer after the agreement expires. This is the "tail" clause, and it is where most post-expiration disputes originate.
Watch Out The most common mistake is signing a listing agreement without a written commission schedule attached. If the split is not documented, disputes at closing favor whoever has the better paper trail, and that is rarely the client.
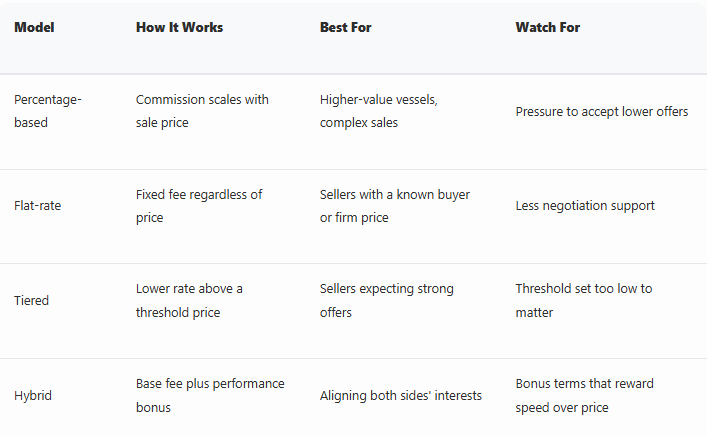
Flat-rate and percentage-based models differ in where the broker's incentive sits. A percentage model rewards a higher sale price; a flat fee removes that incentive but can reduce the broker's motivation to hold firm in negotiation.
When two brokerages are involved, the total commission is divided between them. The listing and selling brokerages negotiate the split before the listing goes live, and it is published to the brokerage community through a multiple listing service or central listing network. A buyer working with their own broker should confirm in writing that the selling side's share is protected, otherwise the buyer's broker may be working for a reduced fee, a conflict the buyer should know about.
When one brokerage represents both buyer and seller, the commission question changes shape. The brokerage may collect both sides of the split or reduce the total. Either is legal in many states with written consent, but the fee structure should be disclosed as part of the dual-agency consent, not discovered at closing.
Three checks catch most problems before closing:
Compare the commission figure in the listing agreement against the closing statement. They should match.
Confirm the split named in the agreement matches the split actually paid.
Confirm any tail clause has a defined expiration date and buyer list, if one exists.
If any fail, request the itemized closing statement and original agreement side by side. The discrepancy is usually clerical, occasionally it is not, which is why the paper trail matters.
A yacht purchase agreement checklist for transparency should confirm that every material term, contingency, and fund movement is documented before any deposit changes hands. Use this as a working list.
Buyer and seller legal names match vessel documentation exactly
Vessel identified by hull identification number, not name alone
Purchase price and deposit amount stated in figures and words
Escrow holder named, with account type and release conditions
Survey and sea trial contingency with a defined deadline
Sea trial conditions specified: sea state, duration, RPM range
Rejection and renegotiation rights spelled out in writing
Closing date, location, and documentation transfer process stated
Commission and fee allocation disclosed on the face of the agreement
Dispute resolution and governing jurisdiction named
Pro Tip Ask for the agreement at least 48 hours before signing. A broker who pressures you to sign the same day is telling you something about how the rest of the transaction will go.
Yacht survey and sea trial standards exist to verify condition independently of what the listing claims. A pre-purchase survey by a surveyor you hired, not one recommended by the seller's broker, is the only condition report that protects your position.
Escrow transparency means every deposit and sale proceeds movement is traceable, held in a segregated account, and released only against written conditions in the purchase agreement. Digital escrow platforms have made this easier to audit and harder to excuse. The mechanics are where the risk lives.
A deposit is not a payment. It is consideration that makes the purchase agreement enforceable, and it should be held by a neutral third party, a title company, escrow agent, or brokerage escrow account, under terms both parties signed. The escrow holder's name, account type, and release conditions belong in the purchase agreement itself, not a side email.
Who holds the funds. Named entity, not "the brokerage."
What account. Segregated client-trust account, not commingled with operating funds.
What releases them. Survey acceptance, sea trial acceptance, document delivery, or a defined closing date, stated as conditions, not intentions.
What happens on rejection. The path back to the buyer if the survey or sea trial fails, including how long the refund takes and who bears the wire costs.
Pro TipAsk for the escrow holder's name and account type in writing before you wire anything. A brokerage that cannot name the escrow holder in one sentence is not holding funds the way you should expect.
Digital escrow platforms have changed fund verification in three ways. Deposit confirmation is near-instant, removing the "check is in the mail" ambiguity that stalled closings. Release conditions can be tied to document delivery, so funds move when the bill of sale and title transfer are confirmed. And transaction records are timestamped, which matters if a dispute arises later.
A proper closing statement itemizes the sale price, commission, fees, credits, and net proceeds to each party. If yours arrives as a single lump figure, request the itemized version before signing. Verify:
Sale price matches the purchase agreement.
Commission matches the listing agreement, including any split.
Escrow, wire, and documentation fees are itemized, not bundled.
Credits for survey findings or repairs appear where the agreement says they should.
Net proceeds to seller and net cost to buyer reconcile against the gross figure.
Cross-border transactions add a layer most buyers underestimate. Funds moving between jurisdictions, flag state registration changes, and currency conversion all create points where transparency can quietly degrade. Three mechanisms to document:
Currency conversion. The rate applied and the date it was locked should be in writing. A rate that floats until closing can move the effective price.
Flag state registration. If the vessel is re-flagged, the registration transfer is a separate step with its own timeline and documentation. Do not assume it happens automatically at closing.
Tax and duty treatment. Import duties, value-added taxes, and state sales tax treatment vary by jurisdiction and by how the vessel is used after closing. Confirm the treatment in writing before funds move.
Five questions, asked in writing, cover most of the exposure:
Who is the escrow holder, and what type of account holds the deposit?
What conditions release the funds, and what happens if those conditions fail?
Which platform or process handles the wire, and has it handled documented vessels before?
If the transaction crosses jurisdictions, what is the currency conversion mechanism and who bears the cost?
When will the itemized closing statement be available for review before signing?
Use this checklist at three points: before signing the listing or buyer agreement, before the survey, and before closing.
Request written commission disclosure before signing anything.
Confirm in writing whether the brokerage is acting as a dual agent.
Ask who holds the deposit and in what type of account.
Get the surveyor's name and confirm they are independent of the seller.
Request the itemized closing statement in advance of closing day.
Confirm which flag state the vessel will be registered under.
Ask for the condition disclosure in writing, not verbally.
Keep every version of every document you sign.
Transparency in a yacht transaction is not something you hope for; it is something you verify at each stage, from the listing agreement through the closing statement. The brokers who resist written disclosure are answering a question you have not asked yet. Spencer Christopher Yacht and Ship builds every engagement around documented commission terms, independent survey coordination, and an in-house closing department that keeps funds and paperwork visible from first showing to delivery.
There is no single federal broker transparency law covering yacht brokerage the way the FMCSA rules apply to freight brokers. Yacht brokerage transparency is governed by a mix of state licensing requirements, industry association standards, and general contract and fiduciary law. Florida, for example, licenses and bonds yacht and ship brokers, and professional bodies like the International Yacht Brokers Association set conduct standards. In practice, transparency comes down to what your listing agreement and purchase agreement require the broker to disclose: commission, dual agency, known defects, and how funds are handled.
Commission is negotiable and varies by vessel size, asking price, and market conditions. A percentage-based structure is the industry convention, with the rate generally declining as vessel value rises. Some brokers offer flat-rate models instead. What matters more than the number is disclosure: the rate, who pays it, and how it splits between listing and buyer brokers should all appear in writing before you sign. Ask for the commission structure in the listing agreement and confirm it again on the closing statement.
Start with state licensing. In Florida, yacht and ship brokers must hold a current, bonded license, which you can verify through the state's business and professional regulation database. Then check industry certifications: the Certified Professional Yacht Broker (CPYB) designation requires documented experience and passing an exam. Membership in the International Yacht Brokers Association or YBBA signals adherence to a code of ethics. A broker with a USCG Master license and prior crew or engineering experience brings hands-on vessel knowledge that is hard to fake.
A transparent purchase agreement names the parties, the vessel (including HIN and documented LOA), the purchase price, and the deposit amount and where it is held. It should spell out contingencies: survey, sea trial, and financing, with deadlines for each. Commission and closing cost allocation belong in writing. The agreement should also state what happens if the survey reveals defects, who bears haul-out and yard costs, and how the escrow account is managed. If any of these terms are vague or missing, ask for them in writing before signing.
BlogLearn how to evaluate sportfish engine hours accurately. Understand duty cycles, maintenance history, and diagnostic tools to assess true engine condition.
 Blog
Follow the steps to buying a luxury yacht in 2026, from title search to survey, closing and delivery. Learn how a fiduciary broker protects your purchase.
 Blog
Luxury yacht brokerage services Florida: compare top firms, learn what to look for in a yacht purchase agreement, and verify broker fiduciary.
Send them over. Every inquiry gets a substantive response within 24 hours, from a person who has read what was asked.